Alawin KYC: Verification Documents, Timing and Withdrawals
 Available in US
Content
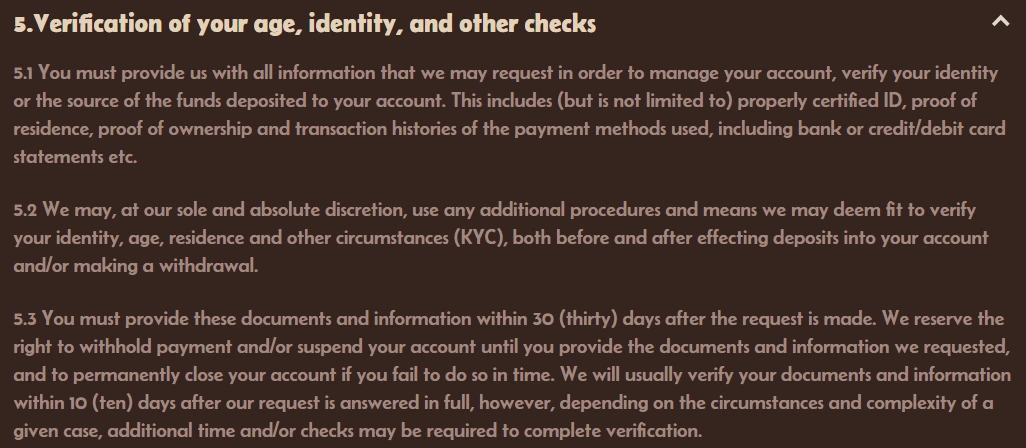
Alawin can ask for information and documents to verify identity, age, residence, payment-method ownership and the source of funds used on an account. Its current Terms name examples that can include properly certified identification, proof of residence, and proof of ownership plus transaction histories for payment methods used. These are examples the operator can request, not a promise that every player receives an identical checklist.
The timing has two separate clocks. Alawin’s current Terms say requested documents and information must be supplied within 30 days after the request is made. Once a request has been answered in full, the operator says verification is usually completed within 10 days, while additional time or checks can be required depending on the case. Payments can be withheld until verification procedures are completed, so KYC can directly affect when a withdrawal moves forward.
What Alawin can verify
The current General Terms give Alawin broad authority to request information needed to manage an account and confirm the person using it. The named areas include identity, age, residence and source of funds. KYC can therefore extend beyond a single photo-ID request and can connect personal details, residence, funding and payment-method ownership.
Alawin also says verification procedures can take place before or after deposits and around a withdrawal. In practical terms, a player who has already deposited should not assume that passing the registration screen means no further checks can occur. A later withdrawal can still trigger identity or source-of-funds review when the operator decides a check is required.
Alawin’s Terms do not set out a separate Australia-only KYC checklist. The same operator terms govern the named document categories, while the earlier account-opening steps are covered under Alawin registration.
Document categories named in the current Terms
Alawin’s current Terms say a verification request can include properly certified ID, proof of residence, and evidence connected with payment methods. For payment methods, the Terms refer to proof of ownership and transaction histories, including bank or credit or debit card statements as examples. The important word is “include”: the Terms present these as possible materials, not as a universal three-document package for every account.
- Certified identification
- This is the identity-document category named in the Terms. The clause does not set one fixed passport, driver-licence or identity-card requirement for every account.
- Proof of residence
- The Terms expressly name proof of residence, but they do not set one guaranteed document format, document age or Australia-specific address rule for every account.
- Payment-method ownership and transaction history
- Alawin can request evidence that the funding method belongs to the account holder and can request transaction histories. This connects KYC with deposits and withdrawals rather than treating identity verification as a separate administrative exercise.
The exact document request depends on the individual account. Follow the wording of the request Alawin sends rather than assuming a generic document list applies to every case.
The named categories cover different parts of the account relationship. Certified identification addresses identity, proof of residence addresses where the account holder lives, and payment-method ownership or transaction history can connect deposits and withdrawals to the person using the account. Alawin can also ask about source of funds. Because these checks can occur before or after deposits and around withdrawals, a request may involve more than the information entered during initial registration.
The timing clauses should also be separated clearly. The account holder has 30 days to provide requested documents and information. After the request has been answered in full, Alawin says the usual processing period is 10 days, while additional time or further checks can apply in more complex cases. An outstanding request can therefore affect a withdrawal even when the general finance-department handling rule is shorter.
The 30-day response window is not the verification time
One of the easiest KYC details to misread is the difference between the time given to the player and the time Alawin says it normally needs after a complete response. The current Terms say requested documents and information must be provided within 30 days after the request. That is the account holder’s response window.
Separately, Alawin says it usually verifies the documents and information within 10 days after its request has been answered in full. The phrase “answered in full” matters. Sending one item from a multi-part request does not start a guaranteed 10-day countdown if other requested information is still outstanding.
The 10-day figure is Alawin’s stated usual period after a complete response, not a fixed deadline or a promise that every account will be cleared in exactly 10 calendar days.
How KYC can affect a withdrawal
Verification is directly connected to payout handling. Alawin’s Terms allow the operator to withhold payment while requested verification documents or information remain outstanding. The withdrawal clauses also allow processing to be delayed while identity, account balance, source of funds and compliance checks are carried out, and the operator can postpone payments until the verification procedures in the Terms are completed.
This means two timelines can overlap. The finance department states that it works through valid withdrawal requests within three business days when the relevant conditions are met and checks are completed. A withdrawal caught in an unresolved KYC review is therefore different from a withdrawal that has already cleared the necessary checks. The three-business-day internal handling statement should not be read as overriding an outstanding verification requirement.
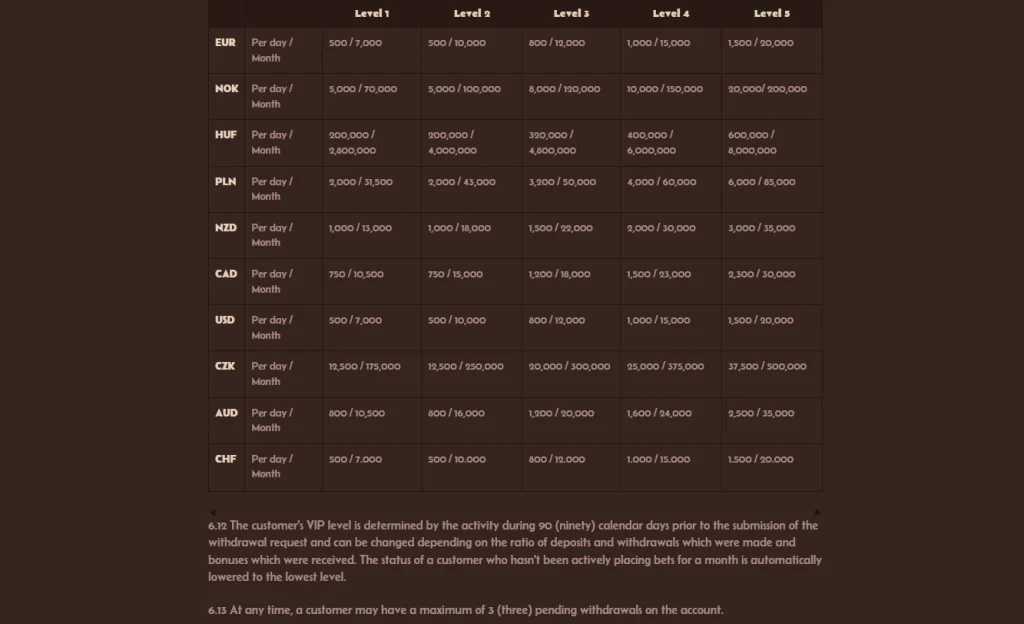
For the current withdrawal limits, pending-request cap and the difference between internal handling and payment-method settlement, see the Alawin withdrawal process. KYC can pause a payout, while the withdrawal limits and processing stages are separate account rules.
Source-of-funds checks
The current Terms expressly allow Alawin to verify the source of funds deposited to an account. They also allow payment-method ownership and transaction histories to be requested. Together, those clauses mean KYC can go beyond a name and date of birth and can extend to information about how account money was funded.
Alawin’s Terms do not state a single threshold at which every Australian user receives a source-of-funds request. They also do not make an identity check equivalent to Australian regulatory approval. Account KYC and local licensing are separate issues.
If Alawin asks for financial records, respond only through the operator’s current authenticated process or support channel and provide only what the request actually requires. This site does not collect KYC files, account numbers, identity documents or transaction histories.
A privacy-conscious preparation checklist
You cannot know the exact request in advance, but you can reduce avoidable friction without uploading sensitive material anywhere unnecessarily.
- Keep registration data consistent. Use your own correct account details so identity and residence evidence do not immediately conflict with the profile.
- Use payment methods you control. The Terms allow Alawin to ask for proof of ownership and transaction history for methods used on the account.
- Read the request line by line. Do not assume a generic internet checklist is the same as the documents requested for your case.
- Separate required data from extra data. Provide what the operator asks for through the official route rather than sending unrelated personal records.
- Check that copies are legible. A complete response is important because Alawin’s stated usual verification period is measured after the request is answered in full.
- Track the request date. The current Terms give a 30-day window to provide requested documents and information.
- Do not treat a pending withdrawal as proof of payment failure. An unresolved verification check can pause payment processing under the Terms.
What happens if the request is not completed
The current KYC clause allows Alawin to withhold payment or suspend an account until requested documents and information are provided. It also says the account can be permanently closed if the requested material is not provided within the stated 30-day period. This is why the response window should not be confused with the operator’s usual verification time.
The practical order is: identify exactly what was requested, supply the complete response within the permitted window, and then distinguish the verification stage from the later movement of funds. If another item is requested, the case can take additional time because the Terms expressly allow further checks for more complex circumstances.
What the 10-day statement does and does not mean
The 10-day statement is useful because it gives a current official benchmark for the verification stage. It is not a guaranteed withdrawal-arrival time, and it is not measured from the date a player first opens an account. It applies after Alawin’s request has been answered in full.
Verification, internal withdrawal handling and later payment-system movement are separate stages and should not be combined into one single payout-time figure.
For a user deciding whether to proceed, the strongest takeaway is not the headline number alone. It is the sequence: request, complete response, verification, withdrawal handling, then payment settlement where applicable. Knowing which stage you are in makes support conversations much more specific.
Australian context without inventing local supervision
Alawin’s KYC requirements come from the operator’s account terms. The regulatory and protection context covers the wider Australian provider-law position separately. That context does not change the document and timing clauses in Alawin’s Terms.
An identity check concerns account verification and does not by itself establish local regulatory approval. KYC requirements and the wider licensing position are separate questions.
Alawin KYC timing and payout impact
Alawin’s current KYC terms are unusually specific on the points that matter most. The operator can verify identity, age, residence, payment-method ownership and source of funds; possible requested materials include certified ID, proof of residence and payment-method ownership or transaction-history evidence. Requested material must be provided within 30 days, and Alawin says verification is usually completed within 10 days after the request has been answered in full, with extra time or checks possible for more complex cases.
The practical risk is a paused payout rather than an abstract paperwork step: the Terms allow payments to be withheld until verification is complete. Use the exact live request for your case, keep the response complete and consistent, and do not send sensitive documents to this website. For the wider product and Australia overview, return to the Alawin Australia review.
This material was created by the Alawin Australia Guide team.
Alawin KYC — More on this topic at alawin casino.
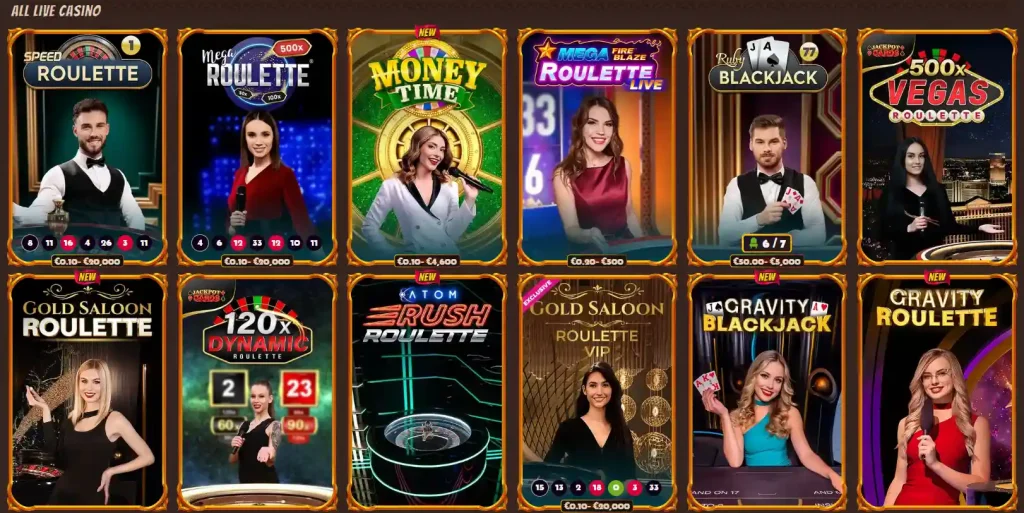
See also Alawin Live Casino.
Related posts
Alawin Withdrawals Australia: AUD Limits, Processing and Checks
Alawin Live Casino: Tables, Live Games and AU Availability